Housebuilder MJ Gleeson has warned that a single delayed land transaction will knock £7.5m off adjusted group profit before tax against current market expectations, as national housebuilders reassess how much land they are willing to buy.
The Yorkshire-headquartered group said its Gleeson Land division had been working towards completing a deal that would account for roughly half of its total forecast plots for the year. That transaction is now unlikely to complete within the current financial year, and two smaller deals have also slipped.
Chief executive Graham Prothero said almost all technical hurdles to disposal of the major site had been cleared. "It is frustrating that completion will now fall into the next financial year. The progress to date should not be underestimated and represents a strong performance by the team."
He added that housebuilders "in the south of England" are reviewing and reappraising land buying strategies, and that he anticipates those conditions continuing through the next financial year — while expressing confidence that demand for high-quality development sites remains intact.
Timing versus value
Two readings of this announcement compete, and they carry very different implications.
The benign one is timing. The site has cleared technical work, demand is described as solid, and the deals are deferred rather than cancelled. On that view the profit has moved across a year-end rather than disappeared, and next year's comparatives should benefit.
The harder reading is that management has told shareholders the same conditions will persist through the next financial year. A delay attributed to counterparties reappraising their strategies is not an administrative slip; it is the transmission of softer end-market demand into the land market. If the buyers are still cautious in twelve months, the deferral becomes a write-down in substance even if it never requires an accounting adjustment.
Both are consistent with what has been said. What distinguishes them is whether national housebuilders resume buying, which is outside Gleeson's control.
Why one deal moves the group's number
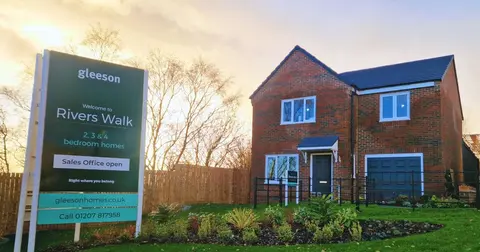
The structure explains the sensitivity. Gleeson operates two businesses: Gleeson Homes, which builds and sells homes in the North of England, and Gleeson Land, which buys land, promotes it through the planning system and sells it to national housebuilders.
Land promotion is a lumpy business. Revenue arrives on completion of a small number of transactions rather than flowing steadily, so a single deal representing about half of forecast plots for the year leaves the division — and hence group profit — dependent on one buyer's timing and financing.
That concentration is normally acceptable because land values appreciate as planning risk is removed. It becomes a problem precisely when purchasers pause, since promotion costs continue to be incurred against income that has slipped, and the pipeline has to be carried for longer.
Note too that the measure cited is adjusted profit before tax. This is not a one-off exceptional item being excluded from view; it is a shortfall in underlying operating performance as management defines it, which is why the market reaction matters more than the headline.
How much is £7.5m
A shortfall needs a denominator. Coverage earlier in the financial year cited analysts' expectation of profit before tax at approximately £24.3m for the year ending June 2026. Against that earlier reference point, £7.5m is around 31%.
That comparison should be used with care: consensus is revised continuously and the figure used for the comparison in the announcement is the contemporaneous one, not the earlier number. Treat the percentage as a sense of scale rather than an exact miss.
Market data around the period showed the shares materially weaker over twelve months and over five years, consistent with a sector that has de-rated rather than with a single company-specific event. Such moves reflect many factors and should not be attributed solely to this announcement.
The second signal in the same news cycle
Gleeson's warning landed alongside one from Bellway, one of the country's largest housebuilders, which flagged an uncertain outlook as global issues weighed on buyer confidence, reported weaker customer demand in recent weeks and said it too was being cautious about buying land.
Two independent participants saying the same thing is worth more than either alone. The mechanism runs in one direction: weaker sales outlets make volume builders protect cash, and the first expenditure deferred is land. Because Gleeson Land's customers are exactly those national builders, their caution is Gleeson's revenue timing.
There is a bifurcation inside that caution worth noting. Both companies say demand for the highest-quality sites continues. What has slowed is appetite for average land, which is what happens when builders have to choose where to commit scarce capital.
What to watch
- The full-year trading update scheduled for 10 July: whether the quantum is confirmed and how much of the shortfall relates to Gleeson Land alone.
- Confirmation of the timing of the major site disposal, and whether it is now contracted or still conditional.
- Commentary on carrying costs and whether any land is reassessed for impairment if delays extend.
- The group's cash position. Deferred completions delay cash as well as profit, while promotion costs continue, so net cash is the number that reveals whether this is cosmetic.
- Statements from Bellway and peers on sales rates. If demand stabilises, delayed land deals can complete quickly; if not, next year's expectations face the same risk.
- Whether the dividend and land-buying plans are maintained, which is management's own statement of confidence.
Sources
- The company update: Gleeson Land's major transaction unlikely to complete in the current financial year, accounting for around half its total forecast plots; two smaller deals also delayed; the combined effect leaving adjusted group profit before tax approximately £7.5m below prevailing market expectations; the statement that national housebuilders are reviewing land buying strategies given current market conditions; the assertion that demand remains solid for high-quality sites; quotations from chief executive Graham Prothero including his comments on cleared technical hurdles, frustration at slippage into the next financial year, southern England land buying conditions expected to persist, and confidence in continued sales of prime sites; and the 10 July full-year trading update date.
- Concurrent reporting that Bellway warned of an uncertain housing market outlook, citing global issues affecting buyer confidence, weaker customer demand in recent weeks and its own caution in land buying.
- Earlier coverage of the group's half-year trading statement citing analysts' profit before tax expectation of approximately £24.3m for the year ending June 2026, used here only as a scale reference.
- Publicly available share price data for the period showing material weakness over one- and five-year horizons.
- Note: the ~31% scale calculation is the author's, derived from figures quoted above and explicitly caveated. Analysis of the timing-versus-value question, division economics and concentration risk, the demand transmission mechanism and the watch list is the author's and not the company's.